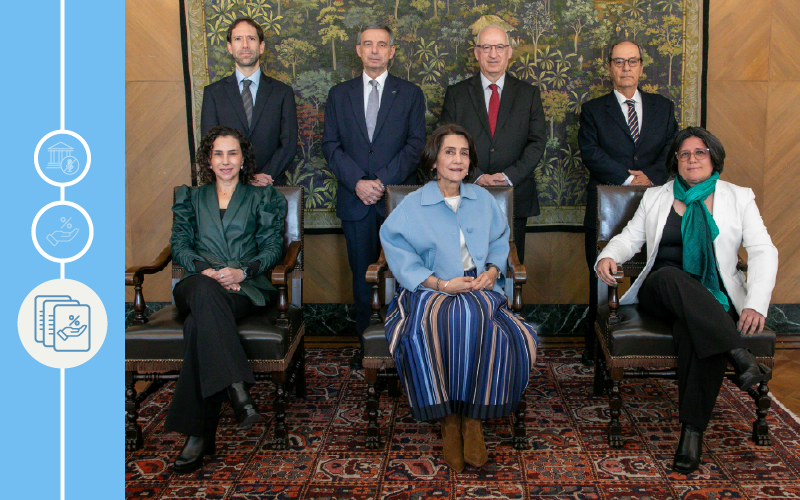

The Board of Directors of Banco de la República decided by majority vote to increase the monetary policy interest rate by 25 basis points (bps) to 12.25%
- Headline inflation increased again, from 6.0% in July to 6.2% in August. The main pressures originated from the food and regulated items groups, whose inflation rates ended August at 6.1% and 6.8%, respectively, while services inflation rebounded from 7.0% to 7.2% between July and August. Core inflation, excluding food and regulated items, increased to 6.1%, reaching its highest level since June 2024. The occurrence of the El Niño phenomenon could continue to place upward pressure on the projected paths of food and regulated-items inflation.
- According to the September survey results, inflation expectations among economic analysts for December 2026 eased in the first quarter following increases in the monetary policy interest rate, but resumed their upward trend in the second quarter, reaching 6.8%. Over a two-year horizon, expectations rose to 4.7% in the first quarter of the year but have since moderated, ending September at 4.0%. Inflation expectations derived from the public debt market remain considerably above the target across all maturities.
- Seasonally adjusted Gross Domestic Product (GDP) recorded annual growth of 3.4% in the second quarter. As in previous quarters, economic activity during this period was driven by final consumption and the strong performance of tertiary sectors such as public administration and art and entertainment activities. The Economic Monitoring Indicator (ISE) suggests that economic activity may have slowed, posting annual growth of 1.1% in July, below the 3.5% recorded in June. The manufacturing industry recorded an annual decline of 2.3%. In contrast, total real retail sales increased by 5.3% year-on-year in July, consistent with annual growth of 22.3% in dollar-denominated imports.
- International financial conditions have tightened slightly amid prospects of a more restrictive monetary policy stance by central banks in advanced economies. This has been associated with currency depreciations against the dollar in emerging economies, including Colombia.
The majority group of directors who voted for a 25-basis-point increase emphasized that headline inflation has continued to rise, reaching levels more than twice the inflation target. This can be attributed not only to pressures from food and regulated items, but also to price increases in many other components of the consumer basket. The latter is mirrored by core inflation, which excludes these items and whose year-on-year increase at the end of August also exceeded 6.0%. These directors warned that inflation’s upward trend could intensify in the short term due to the effects of El Niño on food and regulated item prices, higher energy costs, and increases in oil and agricultural input prices resulting from the conflict in the Middle East. They noted that monetary policy measures were decisive in moderating inflation expectations during the first half of the year. However, expectations continue unanchored from the 3% target, even over longer horizons, diluting some of the increases in the nominal interest rate. They noted that the current macroeconomic situation continues to be characterized by excess demand over output, reflected in a domestic demand that outgrows GDP, which reinforces inflationary pressures and leads to a sharp increase in imports, ultimately expanding the country’s external imbalance. They observed that the tightening of international external financial conditions resulting from recent interest rate increases in advanced economies reduces international investors’ risk appetite, which could generate an increase in the country’s risk premium and a reversal of the exchange rate appreciation, with potential upward effects on prices. These directors acknowledged that this environment of inflationary pressures and risks is characterized by a high degree of uncertainty related to the potential effects of climate and external shocks, as well as the country’s fiscal situation and the scope of the public finance adjustment program undertaken by the new government. One director in this cohort highlighted the advantages of anticipating risk management during the monetary cycle, noting the potential lower costs on long-term growth. For this reason, the director initially voted for a 50-basis-point increase but ultimately supported the 25-basis-point decision in order to secure a majority. Finally, all Board members reiterated the significant contribution that addressing inflationary pressures makes to creating a more favorable environment for promoting saving and boosting private investment.
The directors who voted to keep the policy interest rate unchanged emphasized that the current monetary policy stance is highly contractionary, considering a policy interest rate of 12% in August and annual inflation of 6.2%, which implies an ex post real interest rate close to 6%. They underscored that, despite the 275-basis-point increase in the interest rate since the end of 2025, there is no clear evidence of convergence toward the target. They argued that this may be because the economy is still absorbing the effects of the interest rate increases implemented this year, which they considered plausible given the lags with which monetary policy operates. They added that a significant part of inflation persistence stems from components such as food and regulated items, whose short-term sensitivity to the interest rate is limited. They argued that something similar occurs with services affected by indexation mechanisms such as rents. In this context, they questioned the marginal benefit of further interest rate increases relative to rising costs for economic activity, investment, credit, and the exchange rate. In this regard, one of these directors warned about the risks associated with the type of fiscal adjustment that needs to be undertaken and its consequences for output, employment, and capital accumulation, which affect the capacity to finance spending and service debt. In this context, a more restrictive monetary policy stance, combined with a potential cut in sectors that promote public investment, could have an excessively contractionary effect on output, slowing the already weak growth of the Colombian economy and raising the costs of sustaining the country’s future growth. They warned that a considerable interest rate differential relative to advanced economies still encourages carry trade operations that contribute to pressure for peso appreciation. They stated that the combination of a high real interest rate and the peso’s cumulative appreciation has been deteriorating the financial and competitive conditions of goods-producing and agricultural sectors. Finally, they expressed concern that a more restrictive monetary policy could disproportionately affect vulnerable populations, given the credit and investment needs for reconstruction following the earthquake, coupled with the effects of El Niño on living conditions among those experiencing food insecurity and poverty.
The director who voted for a 50-basis-point increase stated that the balance of inflation risks remains tilted to the upside, starting with an El Niño phenomenon that could reach exceptional intensity. In this scenario, they argued that facing a supply shock with anchored expectations and high credibility is not the same as doing so amid widespread price increases and continued delays in convergence. In this context, they argued for the necessity of a more substantial rise in interest rates to help avoid a longer period of monetary tightness in the future. They insisted that postponing increases in the policy interest rate ultimately results in a greater sacrifice for economic activity. In short, they reaffirmed that waiting does not eliminate the cost but rather shifts it, and may ultimately increase it.
The decision adopted by the Board of Directors maintains a restrictive monetary policy stance, in line with expectations of a declining inflation path in 2027. Future information on the effects of El Niño, the recovery process following the earthquake, and fiscal policy measures will be central to upcoming monetary policy decisions.